Use Bitcoin or crypto with a traditional mortgage

Make your down payment with crypto

Qualify with crypto. Fund with crypto. Keep your assets in self-custody until it's time to close.

Yes — you can use Bitcoin or any supported crypto as the down payment on a traditional mortgage, QM or non-QM. The crypto has to reach escrow as documented U.S. dollars: you send crypto, RealOpen converts it and wires escrow, and your lender gets the paper trail proving the funds were yours. You bring your own lender — RealOpen isn’t one, and nothing here is a crypto-backed loan.

You also don't have to liquidate your portfolio to qualify. RealOpen's RealScore™ verifies your crypto — BTC, ETH, SOL, XRP, stablecoins, and more — so your lender can count it as a reserve asset on your application, even held in cold storage, multisig, or any wallet you control.

When it's time to fund, convert only what the deal needs: you send crypto, we convert it to fiat and wire escrow on your behalf. The rest stays invested. For sellers, agents, and escrow it's a typical financed purchase.

Satisfy the underwriter with RealScore™. Keep full custody the entire time.

How a Crypto Down Payment Actually Works

Yes. You can use Bitcoin or other crypto held in a self-custody wallet for the down payment on a traditional mortgage. RealOpen verifies ownership of the crypto, documents the assets and relevant holding period for the lender, converts the required amount when funding is due, and provides a transaction record tracing the funds from the verified wallet through conversion to the U.S. dollar wire sent to escrow. The lender makes the final underwriting determination.

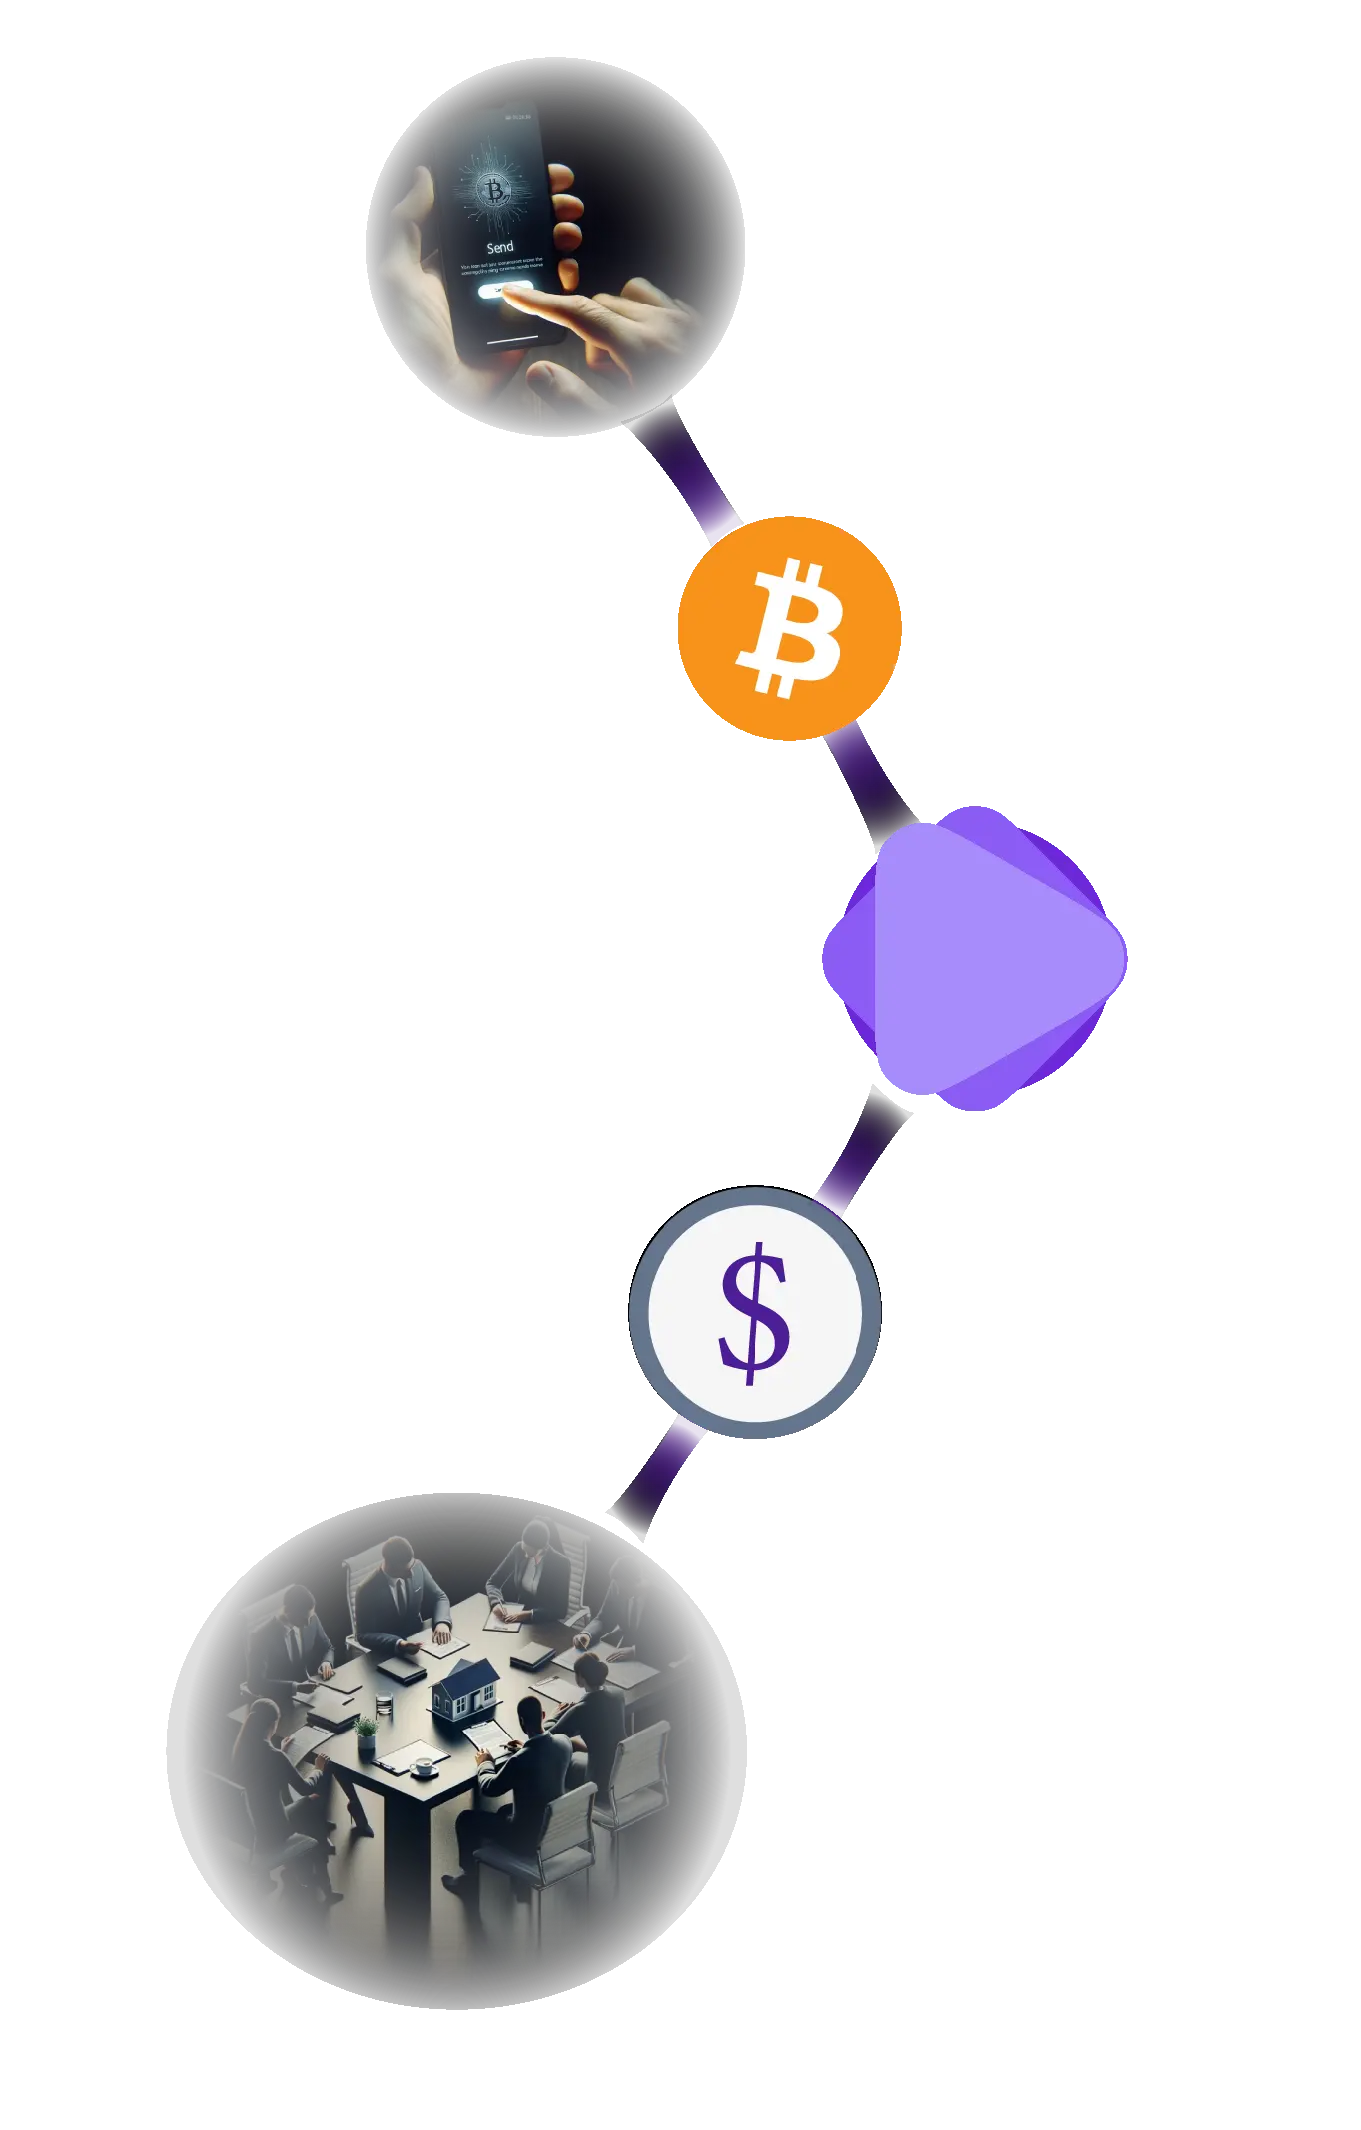
See the complete process — from verifying crypto held in your own wallet to documenting the U.S. dollar wire that reaches escrow.

Can I use crypto for a down payment with a regular mortgage?

Yes. RealOpen turns crypto into a documented down payment on a regular QM or non-QM mortgage from any lender, and the mortgage itself does not change. Your crypto stays in your wallet until closing day; RealOpen converts it and wires escrow, and your lender receives a record tying those dollars to a wallet you provably own.

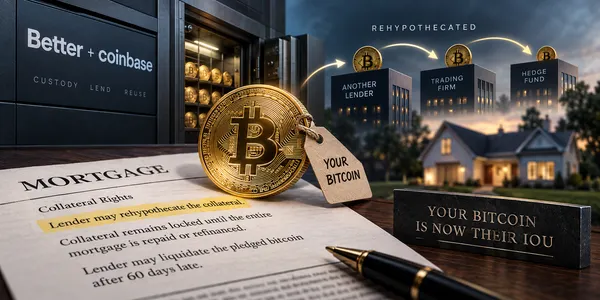
There are three routes to a crypto down payment. Liquidate and season: sell on an exchange, park the cash in a bank, and wait 60 days so the lender doesn’t have to source it. Pledge it: a crypto-backed loan (Better with Coinbase, Milo) holds your coins as collateral. Convert at closing, documented: the route RealOpen runs — no early sale, no 60-day seasoning detour, nothing pledged, no exchange custody.

Fannie Mae’s rule is that virtual currency must be converted to U.S. dollars before it counts; the trail RealOpen produces is what lenders have used to satisfy it. Details in the Fannie Mae crypto down payment guidelines and why you can skip the seasoning trap.

Two ways to use crypto in a financed purchase

Underwriters treat these differently, and so do we. Most buyers end up using both:

  • Qualify with it. Crypto as a reserve asset on your mortgage application. Your holdings strengthen your file without selling a single coin — RealScore™ documents them in a format underwriting can verify.
  • Fund with it. Crypto as the source of your down payment — some or all of it. We convert exactly what you need and wire fiat to escrow, with the sourcing paper trail attached. No 90-day seasoning detour.

Bitcoin-only? No. Any crypto we support works — BTC, ETH, SOL, XRP, stablecoins, and the rest of the accepted list. And note what this page is not: pledging your coins as loan collateral. If you’re weighing that instead, read the crypto-backed mortgage comparison first.

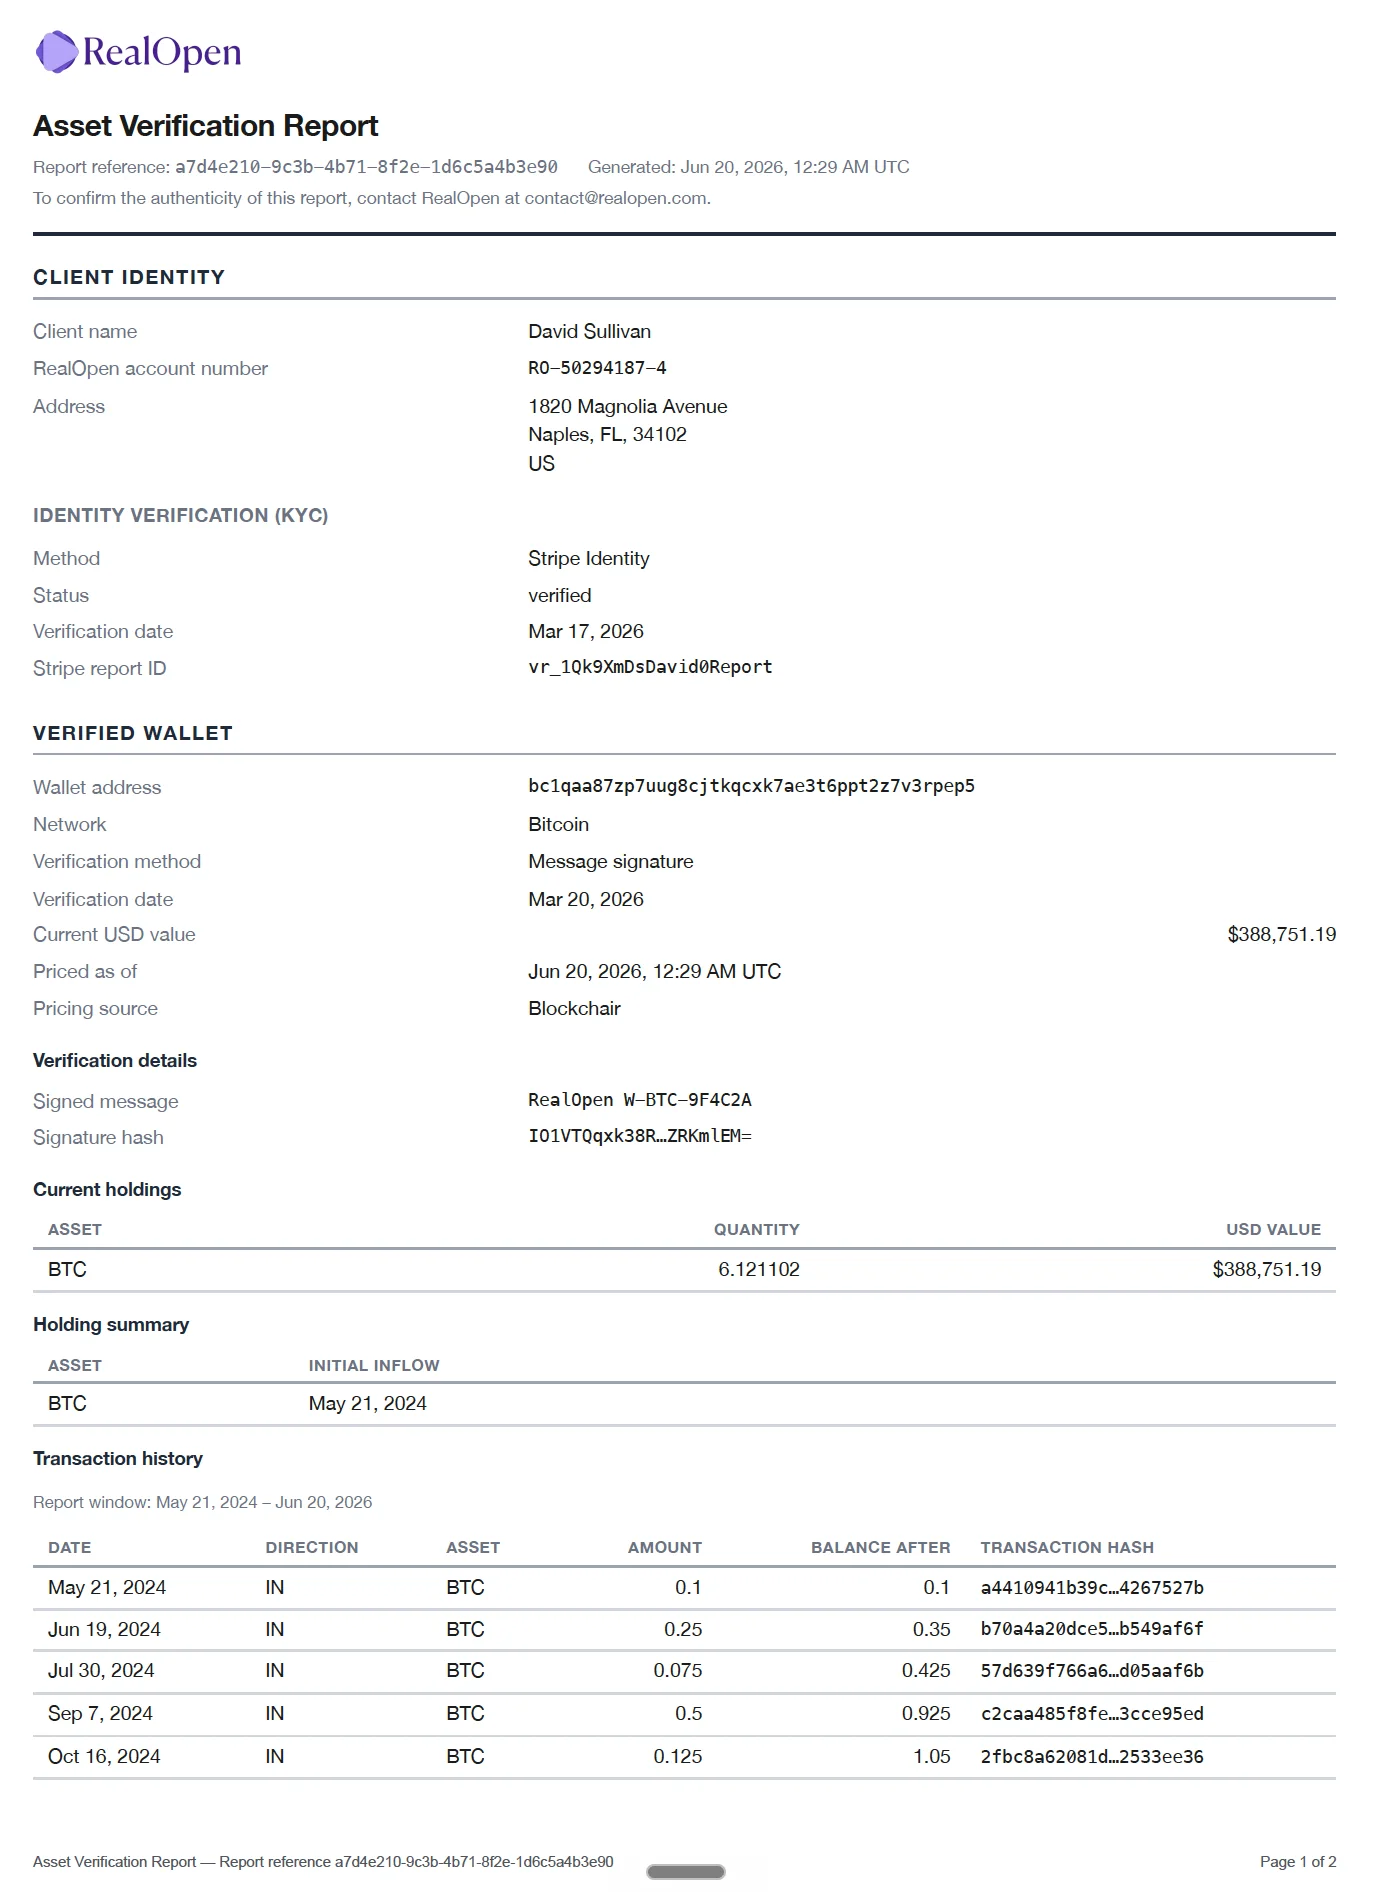
A verified RealScore Report showing crypto held in self-custody

RealScore™ Proves Crypto Reserves

Keep your assets in your wallet. No CEX required.

Fannie Mae says lenders need your crypto on a centralized exchange — with an account statement to prove it. A wallet screenshot won't suffice.

RealScore™ cracks the CEX code, so you don't have to send your coins — or your keys — to centralized crypto purgatory.

  • We verify your holdings across every supported chain—even from cold wallets
  • You get a lender-ready RealScore™ Report
  • No need to move your assets or give up custody

RealScore™ documents what you own, without requiring you to give up control.

TL;DR: Self-custody is no longer a problem. Your crypto can now support a mortgage application.
A RealScore report validating crypto ownership without exchange custody

Why Trust a CEX?

Proof of reserves—without surrendering your keys

Your crypto is likely in self-custody storage for a reason. Moving it to a public, centralized exchange exposes your wealth to legitimate risks:

  • Paused Withdrawals: the classic pre-rug warning
  • Commingled Custody: your assets are now part of their balance sheet
  • Rehypothecation: your assets, someone else's collateral
  • Disappearing Act: FTX, Celsius, BlockFi…

🔥 RealScore verifies your crypto directly from your wallet—cold, hot, or multisig—so you can stay in control while proving reserves.

TL;DR: CEX custody is optional. Proof of reserves doesn't require surrender.
Using crypto to qualify for a mortgage through RealOpen

The Crypto Down Payment Process

From pre-qualification to funding

Just like any financed real estate deal—with a little Web3 swagger:

  • Start your mortgage application (even if you “don't believe in debt”)
  • Onboard with RealOpen and prove you own your wallets — a signed message or a small test transfer from each one
  • Get your RealScore™ Report and hand it to your lender like a boss (they can see how lenders verify it)
  • Find a home, sign a PDF mountain, and enter escrow
  • Send us the contract and escrow contact info
  • Fund by sending crypto from any wallet—cold, hot, multisig, or even a CEX (if you must)
  • We convert your crypto to fiat via a prime OTC desk
  • Fiat gets wired directly to escrow from RealOpen
  • Closing flows like any standard mortgage transaction

No exchange custody. No seller crypto exposure. Just real estate with a crypto core.

Example RealScore Report showing verified crypto holdings for mortgage qualification

A sample RealScore™ Report — verified ownership and balance history

What Lenders Actually Require

The documentation package that closes crypto-funded mortgage deals

Underwriters don’t care about your conviction — they care about source of funds. When a down payment starts as crypto, RealOpen produces the paper trail lenders ask for:

  • RealScore™ Report — verified ownership of your wallets, what they hold, and historical balances and relevant inflows over the seasoning period your lender requires — no exchange custody required
  • Transaction Record — the crypto-to-fiat conversion and wire, documented end to end

Before you move any crypto, ask your loan officer three things: what documentation they accept for crypto assets, what holding (seasoning) period applies, and when the funds have to be in U.S. dollars.

This isn’t theoretical. Traditional-mortgage deals have closed with RealOpen-funded down payments, including a recent one funded in XRP, where the lender required our RealScore™ Report and Transaction Record before releasing loan documents. We produced them. It closed.

TL;DR: Your lender needs paperwork, not a crypto education. We hand them exactly what underwriting asks for.

The seasoning trap: don't sell 90 days early

The most expensive sentence in crypto homebuying is "sell it now and let it season for 60–90 days." It forces your taxable event months early, parks you in cash through whatever the market does next, and delays your offer — all to satisfy a requirement (sourcing) that a documented conversion satisfies directly. If a loan officer has said those words to you, start here: crypto down payment seasoning, explained — or go straight to what to say back to your lender.

Whether you're holding BTC, ETH, SOL, XRP, or stablecoins — RealOpen turns your crypto into real estate on your terms. Create your account, verify your identity, and become a verified buyer in minutes.

Frequently asked questions